Exhibit A -- Specifics of the Loan
Open to Nationwide Accredited Investors ONLY
Loan Number: N2916
Loan Amount: $983,000
Minimum Investment: $20,000
Call for availability of smaller participations
Type: First Trust Deed
Yield: 11.0%*
Target Closing Date: May 8 , 2026
Important Links:
How to Invest in This Loan
Suitability Requirements
Private Placement Memorandum
Loan Servicing Agreement
Audited Financial Statement for B & S
Inventory of Available Loans
To Be Added to Our Investor Email List
PROPERTY
Project: Bozeman MT Commercial Condos II
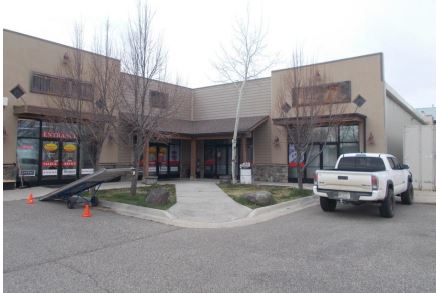
Property Address: 129-135 Prospect Loop, Bozeman, MT, 59718
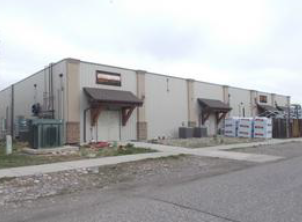
Description: The subject property consists of a 9,821SF commercial condo, located in Bozeman, Gallatin County, MT.
For an aerial view of this property...Click Here!
For a street view of this property...Click Here!
TERMS
Term of Investment |
60 months |
Current Interest Rate |
11.0%* |
Repayment Schedule |
30-Year Amortization |
Monthly Payment |
$9,240.74 * |
Purchase Price of the Note |
$983,000 |
Current Balance on the Note |
$983,000 |
Maturity Date |
60 months |
Balloon Pymt. after 60 months app. |
$974,560.84 |
Late Charge Amount |
$1,079.72 ** |
Prepayment Penalty |
None |
*Net of servicing
**To be shared equally with B&S
EQUITY ANALYSIS
Appraised Value - April 10, 2026 |
$1,690,000 |
Protective Equity - AS-IS |
$707,000 |
| Loan-to-Value - AS-IS | 58.2% |
OPERATING STATEMENT
| INCOME | |
Rental Income |
$148,101 |
Vacancy Allowance (5.0%) |
$7,405 |
Effective Gross Income:
|
$140,696
|
EXPENSES |
. |
Real Estate Taxes |
$12,276 |
Insurance |
$1,473 |
Repairs & Maintenance |
$2,455 |
Management |
$5,628 |
Utilities |
$1,473 |
Reserves for Replacement |
$1,473 |
Total Expenses |
$24,779 |
NET OPERATING INCOME |
$115,917 |
BORROWERS
Name(s) |
LLC |
| Occupation | Real Estate Rentals |
| 2025 Net Business Income | $8,940 |
| 2024 Net Business Income | ($18,124) |
| Percent Ownership | 100% |
Name(s) - Jonny |
Individuals |
| Net Worth | $1,557,683* |
| His Occupation | Technician Manager |
| 2024 Adjusted Gross Income | $93,958 |
| 2023 Adjusted Gross Income | $101,165 |
Name(s) - Stoney |
Individuals |
| Net Worth | $760,050* |
| His Occupation | Retired |
| 2024 Adjusted Gross Income | ($731) |
| 2023 Adjusted Gross Income | $15,814 |
Name(s) - Lynda |
Individuals |
| Net Worth | $1,195,308* |
| Her Occupation | Business Owner |
| 2024 Adjusted Gross Income | $50,933 |
| 2023 Adjusted Gross Income | $51,309 |
|
|
|---|
To invest, please call Justine Smith |
THE LOAN OFFERED HEREBY IS A CANNABIS LOAN THAT WILL BE SECURED BY A PROPERTY UTILIZED TO GROW, MANUFACTURE, PROCESS, DISTRIBUTE OR DISPENSE CANNABIS OR CANNABIS RELATED PRODUCTS. THIS LOAN INVOLVES SIGNIFICANT ADDITIONAL RISKS NOT ATTRIBUTABLE TO LOANS UNRELATED TO THE CANNABIS INDUSTRY AND SUCH LOANS ARE NOT SUITABLE FOR ALL INVESTORS. POTENTIAL PURCHASERS OF FRACTIONAL INTERESTS IN THIS LOAN MUST REVIEW AND UNDERSTAND THE INFORMATION SET FORTH IN THE OFFERING CIRCULAR ENTITLED "ADDITIONAL RISKS AND CONSIDERATIONS OF CANNABIS RELATED LOANS" PRIOR TO INVESTING. PURCHASERS OF INTERESTS IN THIS LOAN SHOULD ALSO CONSULT THEIR OWN LEGAL COUNSEL AND INVESTMENT ADVISORS WITH RESPECT TO THESE RISKS TO DETERMINE IF AN INVESTMENT IN THIS LOAN IS APPROPRIATE FOR THEIR PARTICULAR RISK TOLERANCE PROFILE AND FINANCIAL SITUATION.
BOZEMAN MT COMMERCIAL CONDOS II
George Says: "This is an above-average hard money loan. All three borrowers have very good credit, arguably excellent credit. The property is quite desirable. Bozeman is also a desirable town, a destination for many fleeing the ills of broken cities."
Blackburne & Sons is pleased to present this First Trust Deed secured by a 9,821 square foot commercial condominium comprised of three units, located in Bozeman, Gallatin County, Montana.
The purpose of this in-house refinance is to pay off the existing Blackburne & Sons loan in the amount of $755,000, satisfy the second deed of trust in the amount of $172,400 that has been called due, and cover closing costs.
COUNTY INFORMATION
Gallatin County is located in the state of Montana, with its county seat in Bozeman. It is one of the fastest-growing counties in the state, with a population of approximately 118,960 as of the 2020 Census. The area benefits from its proximity to Yellowstone National Park and Big Sky Resort, as well as tourism and recreational activity in the surrounding mountain ranges and river systems.
CITY INFORMATION
Bozeman is located in southwest Montana and serves as the county seat of Gallatin County. The city had a population of 53,293 as of the 2020 Census and is part of the Bozeman Micropolitan Statistical Area, which includes all of Gallatin County. The local economy is supported by Montana State University, tourism, retail trade, and service industries.
SUBJECT PROPERTY DETAILS
The subject is an existing commercial condominium containing a total of 9,821 square feet of gross leasable area, comprised of three units. The improvements were constructed in 2007 and the property is approximately 89% leased, with the remaining area owner occupied. The site consists of approximately 0.23 acres and includes common area access and parking. The property is zoned for commercial use, is legally conforming, and is located in a low-risk flood zone (Zone X). The building is constructed of metal (Class “S”) materials and features storefront-style entrances, with parking available both directly in front of the units and within a shared common parking area.
The property generates gross monthly rental income of approximately $11,345. Common area maintenance (CAM) charges are approximately $2,000 per month, the majority of which tenants reimburse.
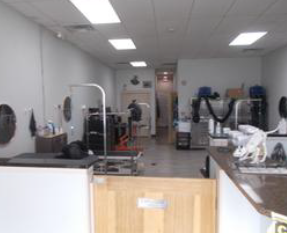
Suite 1 contains 1,403 square feet and is leased to a pet grooming business. The tenant pays $1,545 per month. The lease began in December 2024 and currently operates on a month-to-month basis with annual 3% increases.
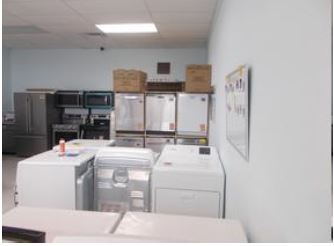
Suite 2 contains 1,037 square feet and is owner-occupied as an appliance store. Market rent is approximately $2,300 per month on a NNN basis, with a lease term extending through December 2028.
Suite 3 contains 7,381 square feet and is leased to a tenant utilizing the space as a cannabis grow facility. The tenant pays $7,500 per month plus 60% of CAM charges. The current lease expires in December 2026 and includes 5% annual increases after the initial term.
BORROWER SUMMARY
The borrowing entity is a limited liability company owned equally by three guarantors (a mother and her two sons), all of whom will provide personal guarantees on the loan. Their spouses will not be on our loan or provide a personal guarantee. The entity focuses on property management and reported net business income of $8,940 in 2025 and ($18,124) in 2024, with income impacted by interest and depreciation.
The borrowers purchased the subject property in 2010 for $970,000. Blackburne & Sons funded a loan on the property in 2024 for $760,000 to refinance a maturing bank loan. At that time, a second lien remained subordinate. The second lien holder has since called the note due, and this refinance will satisfy that obligation.
GUARANTOR SUMMARY
JW is a married man who works as an appliance technician for his appliance repair business located within the subject property. He reports a net worth of approximately $1,557,683 and a mid-credit score of 768. His adjusted gross income was $93,958 in 2024 and $101,165 in 2023.
SW is an unmarried man who is a retired disabled veteran and serves as general manager of the appliance business. He reports a net worth of approximately $760,050 and a mid-credit score of 815. His adjusted gross income was ($715) in 2024 and $15,814 in 2023.
LW is a married woman who serves as Chief Financial Officer of the borrowing entity. She reports a net worth of approximately $1,195,308 and a mid-credit score of 750. Her adjusted gross income was $50,933 in 2024 and $51,309 in 2023.
All three guarantors have filed an extension for the 2025 tax year.
VALUATION SUMMARY
We hired an MAI appraiser who gave this property an (AS-IS) Appraised Value of $1,690,000. This was the same appraiser who appraised the property back in 2024. Please note, we did not order a new BPO but ordered one in 2024 that will be in the package for review. The 2024 BPO came in at $2,064,000. We did not order a new environmental report but will have the 2024 environmental in the due diligence package for review.
At an 11.0% yield to the investors and a 58.2% LTV (AS-IS APPRAISED VALUE), this appears to be a reasonable investment. Investing in any first trust deed involves substantial risk, so be sure to read the Risk Factors section of the Offering Circular carefully before investing. A large and prolonged decline in real estate values is possible. Foreclosed commercial properties almost always need to be renovated before they can be leased or sold, so be sure to maintain some liquidity.
ACCREDITATION STANDARDS
Please note this offering is a SEC Regulation D filing and will be done through a Private Placement Memorandum. In order to invest, you must be an accredited investor. Generally speaking, an accredited investor is an individual:
(a) whose individual income exceeds $200,000 in each of the past two years, with reasonable expectation of reaching the same going forward OR
(b) whose joint income with spouse exceeds $300,000 in each of the past two years OR
(c) your NET WORTH exceeds $1,000,000 (exclusive of your primary residence) OR
If you plan on investing through an entity, the entity can qualify if ANY of the following are met:
(a) all equity owners must be accredited OR
(b) any trust with more than $5,000,000 in assets OR
(c) ERISA with either $5,000,000 in assets OR a bank, insurance company, or registered investment advisor as it's trustee OR
(d) any self directed ERISA with an accredited investor(s) making the business decisions OR
(e) an IRA owned by an accredited investor
George’s Advice For Successful First Mortgage Investing
- You should spread your mortgage investment portfolio out among lots of different deals. If you have $300,000 to invest, you should invest $10,000 to $20,000 in 15 to 20 different fractionalized first trust deeds. For example, if the deal is a $300,000 first trust deed on an office building in Boise, with a $15,000 investment you would own 5% of the loan. By spreading your money out into a bunch of different deals, you are achieving the diversity of a fund without the failed fund sponsor problem. If you are extremely wealthy, you could double (or even triple) my suggested investment amounts, but be careful about pouring too much money into a single deal. We once had a whole building fall into an old coal mine. Ouch.
- Be wise and resist investing in any first trust deed yielding more than 9%. I would personally never invest in a first trust deed with a double-digit yield. The payments slowly grind the borrowers into the dust.
- Blackburne’s Law theorizes that a portfolio of 8% and 9% first trust deeds will outperform a portfolio of 11% and 12% first trust deeds over a seven-year term. Only our wisest (and eventually the happiest) investors listen to me.
- You can also buy some of our smaller deals in their entirety, but I only recommend this if you are richer than Crassus.
- It is very easy to lose money in hard money first mortgages, so fight-fight-fight against the temptation to invest in high-yield deals. As Nancy Reagan used to say, “Just say no.” But if you choose 7% to 9% first mortgages, I predict that you will be very, very pleased.
- During the S&L Crisis, commercial real estate fell by 45%. Within three years of hitting bottom, values reached new highs. During the Dot-Com Meltdown, commercial real estate fell by 45%. Within three years of hitting bottom, values reached new highs. During the Great Recession, commercial real estate fell by 45%. Within three years of hitting bottom, values reached new highs. Some time in the next decade, we will have another opportunity to snatch up prime commercial real estate at a huge discount. You will be terrified, but when Blackburne and Sons invites you to join a syndicate to buy a nice commercial property at a 35% discount off its prior high, just remember that the best time to invest is when blood is running in the streets. Why not when real estate has fallen by 45%? You’ll never catch the very bottom because historically the bounces off the bottom happen much too fast. Bounce-soar. You will be terrified, but just remember that the best time to invest is when blood is running in the streets.
Earn a $250 Referral Fee |
To invest, please call Justine Smith |
Blackburne & Sons Realty Capital Corporation--For more information, contact Justine Smith
555 University Ave., Suite 150, Sacramento, CA 95825
Telephone: (916) 338-3232 * Fax: (916) 338-2328
Real Estate Broker -- California Department of Real Estate -- License Number 829677 -- NMLS Number 103430
Publicly advertised to California residents only under California Department of Business Oversight business plan permit.
Return to C-Loans Home Page | Return to Blackburne & Sons Home Page
Copyright © 2025 Blackburne & Sons Realty Capital Corporation. All rights reserved. (800) 606-3232