Exhibit A -- Specifics of the Loan
Open to Nationwide Accredited Investors ONLY
Loan Number: N2927
Loan Amount: $211,250
Minimum Investment: $10,000
Call for availability of smaller participations
Type: First Deed of Trust
Yield: 9.0%*
Target Closing Date: August 21, 2026
Important Links:
How to Invest in This Loan
Suitability Requirements
Private Placement Memorandum
Loan Servicing Agreement
Audited Financial Statement for B & S
Inventory of Available Loans
To Be Added to Our Investor Email List
PROPERTY
Project:
Mississippi 2-Unit Retail Refinance
Property Address: 3116 East Shiloh Road, Corinth, MS 38834
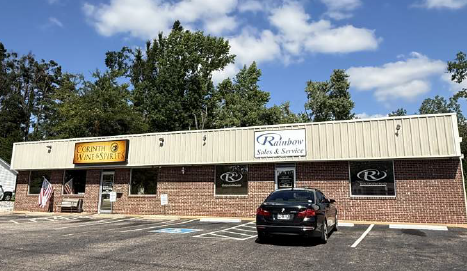
Description: The subject property consists of a 2 unit 4,800SF retail building on 0.50-acres located in Corinth, Alcorn County, MS.
For an aerial view of this property...Click Here!
For a street view of this property...Click Here!

TERMS
Term of Investment |
60 months |
Current Interest Rate |
9.0%* |
Repayment Schedule |
30-Year Amortization |
Monthly Payment |
$1,661.36* |
Purchase Price of the Note |
$211,250 |
Current Balance on the Note |
$211,250 |
Maturity Date |
60 months |
Balloon Pymt. after 60 months app. |
$207,140.58 |
Late Charge Amount |
$199.58** |
Prepayment Penalty |
None |
*Net of servicing
**To be shared equally with B&S
EQUITY ANALYSIS
Appraised Value - July 21, 2026 |
$325,000 |
Protective Equity - AS-IS |
$113,750 |
| Loan-to-Value - AS-IS | 65.0% |
OPERATING STATEMENT
| INCOME | |
Rental Income |
$40,800 |
Vacancy Allowance (5.0%) |
$1,224 |
Effective Gross Income:
|
$39,576
|
EXPENSES |
. |
Property Taxes |
$3,604 |
Insurance |
$2,880 |
Management |
$1,200 |
Reserves for Replacement |
$2,400 |
Total Expenses |
$10,084 |
NET OPERATING INCOME |
$29,492 |
BORROWERS
Name(s) |
LLC |
| Occupation | Real Estate Rentals |
| 2025 Net Business Income | ($165,052) |
| Percent Ownership | 100% |
Name(s) |
Individual |
| Net Worth | $578,976* |
| His Occupation | Sales Manager |
| 2025 Adjusted Gross Income | ($52,930) |
| 2024 Adjusted Gross Income | $10,083 |
Name(s) |
Individual |
| Net Worth | $4,615,190* |
| His Occupation | Business Owner |
| 2025 Adjusted Gross Income | $186,583 |
| 2024 Adjusted Gross Income | $197,406 |
|
|
|---|
To invest, please call Justine Smith |
MISSISSIPPI 2-UNIT RETAIL REFINANCE
George Says: "Heavens, I love small deals. Small loans have small payments, which are much easier to make. I wish we had a dozen more little deals like this."
Blackburne & Sons is pleased to present this First Trust Deed secured by a 2 unit 4,800SF retail building on 0.50-acres located in Corinth, Alcorn County, Mississippi.
The proceeds from this cash-out refinance will be used to support the continued growth of the guarantor’s real estate investment business. Specifically, a portion of the funds will be used to assist with the down payment for the acquisition of a portfolio of 47 single-family rental homes as part of a multi-million-dollar transaction. Per the guarantor, this acquisition is expected to increase their monthly rental revenue by approximately $60,000.
The remaining proceeds will provide working capital for the development of their seven-home residential subdivision, supporting infrastructure, construction, and other development costs associated with the project.
This property is free and clear of any liens or mortgages.
COUNTY INFORMATION
Alcorn County is a county located in the northeastern portion of the U.S. state of Mississippi. As of the 2020 census, the population was 34,740. Its county seat is Corinth. The county is named in honor of Governor James L. Alcorn. The Corinth Micropolitan Statistical Area includes all of Alcorn County.
According to the U.S. Census Bureau, the county has a total area of 401 square miles, of which 400 square miles is land and 1.3 square miles (0.3%) is water. It is the smallest county by area in Mississippi. The Tuscumbia and Hatchie rivers intersect the county.
CITY INFORMATION
Corinth is a city in and the county seat of Alcorn County, Mississippi, United States. The population was 14,622 at the 2020 census. Its ZIP codes are 38834 and 38835. It lies on the state line with Tennessee. According to the United States Census Bureau, the city has a total area of 30.3 square miles, of which 30.2 square miles is land and 0.12 square miles, or 0.43%, is water.
In 2024, the median property value in Corinth, MS was $177,100, with a home ownership rate of 50.5%, and the median household income was $44,226. The economy of Corinth, MS employs 6,010 people. In 2024, the largest industries in Corinth, MS were Manufacturing (1,223 people), Health Care & Social Assistance (989 people), and Retail Trade (755 people), and the highest paying industries were Administrative & Support & Waste Management Services ($92,917), Professional, Scientific, & Management, & Administrative & Waste Management Services ($78,483), and Professional, Scientific, & Technical Services ($78,438).
SUBJECT PROPERTY DETAILS
The subject site is a single parcel containing 0.5-acres. It irregular in shape and generally level in topography. The subject is located along Shiloh Road, a heavily traveled thoroughfare, located just north of Kendrick Road.
The subject’s neighborhood consists of industrial and offices uses. Properties around the subject include retail facilities, office facilities, auto facilities, convenience stores and residential properties.
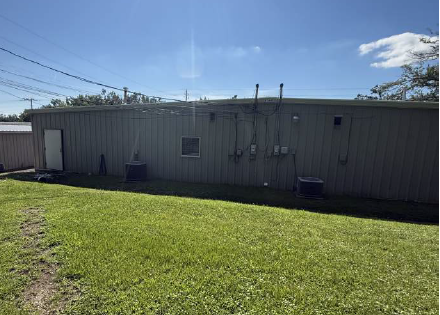
The subject site is improved with a steel frame, metal clad building with a brick façade and metal, gabled roof on a concrete slab foundation. It totals approximately 4,800 SF in size and has 2-units. The facility is heated and cooled by central units and was built in 2001.
The building is divided in half by an interior wall and includes two (2) main units. Each unit includes an open general office/retail area, individual offices/rooms, a storage area and a restroom. The interior of the facility generally consists of carpeted and vinyl flooring, drywall walls, and acoustical drop-in tile ceilings. Site improvements include asphalt drive and parking area, concrete walkways, and adequate landscaping. The drive and parking area is approximately 7,000 square feet in area.
The property is currently 100% leased. One unit is leased to the guarantor’s business for $1,800 per month, and other unit is leased to a liquor store for $1,000 per month. Both leases are set to expire in December of 2026. This property is free and clear of any liens or mortgages.
BORROWER SUMMARY
The borrower is a Limited Liability Company (LLC) that is registered in the state of Mississippi and owned 50/50 by our guarantors. The LLC specializes in real estate investments, and was formed in March of 2025. It reported a net business loss of ($165,052) in 2025. We were also provided a 2026 YTD (through June 2026) profit & loss statement showing net income of $15,643.28.
Per the borrower: “During the preparation of our refinance package, we discovered that rental income from the office building owned by our LLC was inadvertently omitted from our 2025 tax return due to a reporting error. This was an unintentional reporting error that resulted in our taxable income being understated, not overstated. We have contacted our CPA to review the return and prepare an amended return."
"Our LLC acquired the property on April 1, 2025, and the building has remained continuously occupied by two tenants generating a combined monthly rental income of $2,800. ”
GUARANTOR SUMMARY
Guarantor #1 is a married man who works as a sales manager. His wife will not be on our loan or providing a personal guarantee. He reported an adjusted gross income of ($52,930) in 2025 and $10,083 in 2024. This guarantor has a mid-credit score of 647 and self-reported a net worth of $578,976. He is the son-in-law of guarantor #2.
Per the borrower, “The losses reflected on my 2025 federal income tax return were primarily the result of non-cash depreciation and other allowable deductions associated with my rental real estate investments.”
“In addition, during 2025 we made significant investments in improving our rental portfolio, including replacing multiple HVAC systems, installing new flooring, and completing other property improvements.”
“These investments were made to improve the long-term value and performance of the portfolio. As a result, the taxable income reported on my return does not fully reflect the cash flow generated by our real estate operations.”
Guarantor #2 is a married man who works as the owner of the sales company. His wife will not be on our loan or providing a personal guarantee. He reported an adjusted gross income of $186,583 in 2025 and $197,486 in 2024. His has a mid-credit score of 763, and he self-reports a net worth of $4,615,190. This guarantor is the sole owner of another Limited Liability Company (LLC) that will be providing a corporate guarantee on this loan. It specializes in sales and was formed in July of 2016. It reports its income through the guarantor’s personal tax returns.
VALUATION SUMMARY
We hired a general certified appraiser who valued this property at $325,000 (AS-IS). We also hired a broker to perform a Broker’s Price Opinion (BPO) who valued the property at $323,000.
At a 9.0% yield to investors and a 65.0% LTV (AS-IS), this appears to be a reasonable investment. Investing in any first mortgage involves substantial risk, so be sure to read the Risk Factors section of the Offering Circular carefully before investing. A large and prolonged decline in real estate values is possible. Foreclosed commercial properties almost always need to be renovated before they can be leased or sold, so be sure to maintain some liquidity.
ACCREDITATION STANDARDS
Please note this offering is a SEC Regulation D filing and will be done through a Private Placement Memorandum. In order to invest, you must be an accredited investor. Generally speaking, an accredited investor is an individual:
(a) whose individual income exceeds $200,000 in each of the past two years, with reasonable expectation of reaching the same going forward OR
(b) whose joint income with spouse exceeds $300,000 in each of the past two years OR
(c) your NET WORTH exceeds $1,000,000 (exclusive of your primary residence) OR
If you plan on investing through an entity, the entity can qualify if ANY of the following are met:
(a) all equity owners must be accredited OR
(b) any trust with more than $5,000,000 in assets OR
(c) ERISA with either $5,000,000 in assets OR a bank, insurance company, or registered investment advisor as it's trustee OR
(d) any self directed ERISA with an accredited investor(s) making the business decisions OR
(e) an IRA owned by an accredited investor
George’s Advice For Successful First Mortgage Investing
- You should spread your mortgage investment portfolio out among lots of different deals. If you have $300,000 to invest, you should invest $10,000 to $20,000 in 15 to 20 different fractionalized first trust deeds. For example, if the deal is a $300,000 first trust deed on an office building in Boise, with a $15,000 investment you would own 5% of the loan. By spreading your money out into a bunch of different deals, you are achieving the diversity of a fund without the failed fund sponsor problem. If you are extremely wealthy, you could double (or even triple) my suggested investment amounts, but be careful about pouring too much money into a single deal. We once had a whole building fall into an old coal mine. Ouch.
- Be wise and resist investing in any first trust deed yielding more than 9%. I would personally never invest in a first trust deed with a double-digit yield. The payments slowly grind the borrowers into the dust.
- Blackburne’s Law theorizes that a portfolio of 8% and 9% first trust deeds will outperform a portfolio of 11% and 12% first trust deeds over a seven-year term. Only our wisest (and eventually the happiest) investors listen to me.
- You can also buy some of our smaller deals in their entirety, but I only recommend this if you are richer than Crassus.
- It is very easy to lose money in hard money first mortgages, so fight-fight-fight against the temptation to invest in high-yield deals. As Nancy Reagan used to say, “Just say no.” But if you choose 7% to 9% first mortgages, I predict that you will be very, very pleased.
- During the S&L Crisis, commercial real estate fell by 45%. Within three years of hitting bottom, values reached new highs. During the Dot-Com Meltdown, commercial real estate fell by 45%. Within three years of hitting bottom, values reached new highs. During the Great Recession, commercial real estate fell by 45%. Within three years of hitting bottom, values reached new highs. Some time in the next decade, we will have another opportunity to snatch up prime commercial real estate at a huge discount. You will be terrified, but when Blackburne and Sons invites you to join a syndicate to buy a nice commercial property at a 35% discount off its prior high, just remember that the best time to invest is when blood is running in the streets. Why not when real estate has fallen by 45%? You’ll never catch the very bottom because historically the bounces off the bottom happen much too fast. Bounce-soar. You will be terrified, but just remember that the best time to invest is when blood is running in the streets.
Earn a $250 Referral Fee |
To invest, please call Justine Smith |
Blackburne & Sons Realty Capital Corporation--For more information, contact Justine Smith
555 University Ave., Suite 150, Sacramento, CA 95825
Telephone: (916) 338-3232 * Fax: (916) 338-2328
Real Estate Broker -- California Department of Real Estate -- License Number 829677 -- NMLS Number 103430
Publicly advertised to California residents only under California Department of Business Oversight business plan permit.
Return to C-Loans Home Page | Return to Blackburne & Sons Home Page
Copyright © 2026 Blackburne & Sons Realty Capital Corporation. All rights reserved. (800) 606-3232